The Sales Comparison Approach in Commercial Real Estate
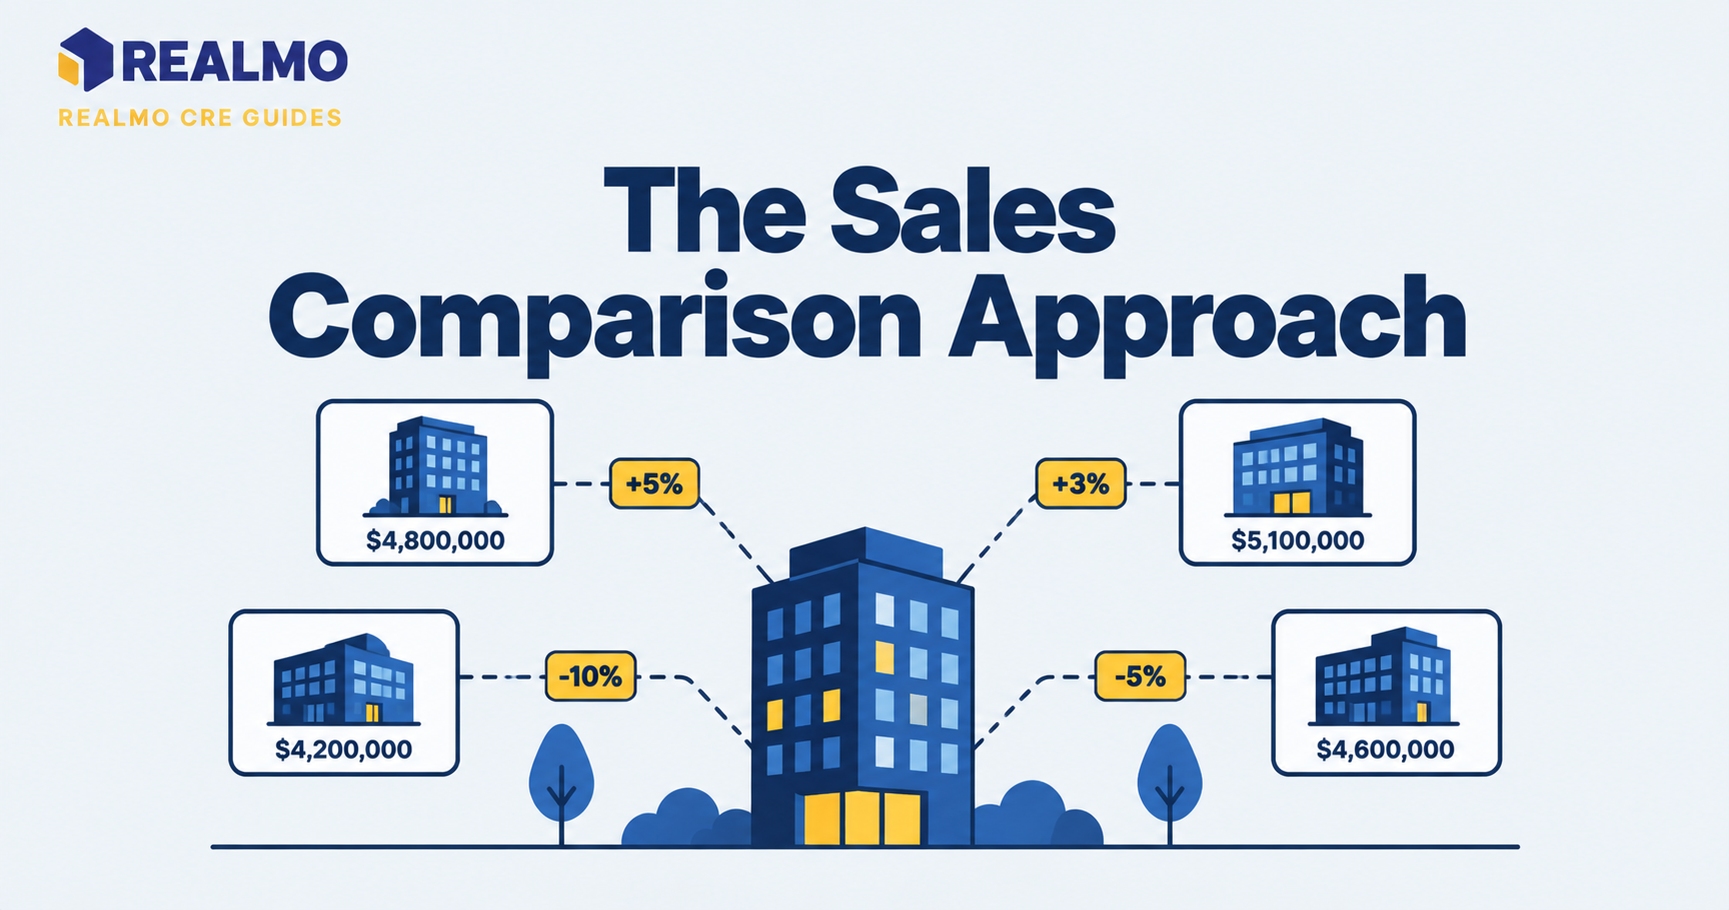
The sales comparison approach estimates value from recent sales of similar properties. Each sale is adjusted for location, size, condition, and transaction terms. The adjusted prices produce a range of value indications, which the analyst reconciles into a single supported conclusion for the subject property.
Why brokers get challenged on their comps
A broker presenting a pricing recommendation rarely gets pushed back on the arithmetic. The pushback lands on comp selection. An owner who believes the property is worth more will ask why the sale two blocks north was excluded. A buyer’s representative may challenge a 15-year corporate-lease comp. It is not equivalent to a building with three local tenants on month-to-month terms.
Both questions are attacks on the same weak point: unstated judgment. Comp selection and adjustment are judgment calls, and judgment that cannot be traced back to evidence collapses under scrutiny. Brokers should show why each sale was included, what was adjusted, and where the number came from. That evidence survives listing, appraisal review, and negotiation.
How the sales comparison approach works
The approach rests on substitution. A buyer will pay no more for a property than the cost of acquiring an equally desirable substitute. If three comparable buildings traded within the past year, the subject should sell within a defensible distance of those prices once differences are accounted for.
Execution follows a fixed sequence. Define the subject and the interest being valued. Gather sales of properties that compete for the same buyer pool. Verify each transaction with a party to the deal. Select a unit of comparison. Adjust each sale for differences relative to the subject. Reconcile the adjusted indications into a value conclusion.
The adjustments always move the comparable toward the subject, never the reverse. A superior comp is adjusted downward to estimate what it would have sold for as the subject. Reversing that direction is the most common mechanical error in the method and roughly doubles the adjustment error.
The approach carries the most weight when buyers price the asset itself rather than its income. Examples include land, owner-user properties, user-bought retail, and small mixed-use assets. For leased investment property, it works alongside the income approach to value rather than replacing it.
What qualifies a sale as comparable
Comparability is defined by competition, not by proximity. Two buildings on the same street can serve different buyer pools. A sale forty miles away in a similar submarket may provide better evidence.
Five screens filter the data set. Property type and highest and best use must match; a warehouse purchased for redevelopment is not a comp for a warehouse purchased for distribution. Market area must expose the property to the same demand. Physical characteristics (size, age, clear height, parking ratio, frontage) should fall within a range the market treats as substitutable. Transaction date must be recent enough that market conditions can be measured rather than guessed. The property rights conveyed must be identifiable: fee simple, leased fee, or leasehold.
Verification separates usable data from noise. A recorded price tells you what changed hands on paper. A recorded price omits important deal facts. It does not reveal below-market seller financing, assumed lease obligations, portfolio allocations, or related parties. Confirming those facts with the broker, buyer, or seller is what converts a recorded transfer into evidence. Ownership records and sale histories on Realmo’s property analytics shorten the identification step, but the confirmation call still has to happen.
The order in which adjustments are applied
Adjustments are not interchangeable. Apply transaction-related adjustments first and sequentially to the running price. Each adjustment restates the sale as if a different transaction condition had existed. Property-related items are applied afterward to that adjusted figure.
- Real property rights conveyed, fee simple versus a leased fee encumbered by an above- or below-market lease.
- Financing terms, seller carryback or assumed debt at off-market rates creates cash-equivalency differences.
- Conditions of sale, atypical motivation, such as a 1031 deadline, an assemblage premium, or a distressed seller.
- Expenditures made immediately after purchase, deferred maintenance, environmental remediation, or lease-up costs the buyer knowingly absorbed as part of the price.
- Market conditions, the change in pricing between the comp’s contract date and the subject’s effective date, called the time adjustment.
- Physical, locational, and economic characteristics, size, age, condition, access, corner exposure, tenant credit, remaining lease term.
Two details matter for accuracy. Market conditions are measured from the contract date, not the closing date, because price is agreed when terms are struck. Expenditures made after purchase are added to the price paid before other adjustments, since the buyer’s total commitment is the real indication of value.
How to derive adjustment amounts from data
Adjustments pulled from intuition are the fastest way to lose an argument. Four derivation methods produce numbers that can be defended.
Paired data analysis isolates a single variable by comparing two sales that differ in one meaningful respect. Two identical suburban office buildings, one with structured parking and one without, price the parking difference directly. Clean pairs are rare. Analysts therefore compare grouped sales and accept a wider confidence band around the result.
Cost-based adjustment applies to curable physical differences. A comp needing a roof replacement receives an upward cost-to-cure adjustment. The logic is that the buyer discounted price by roughly the repair cost. Depreciated cost, not replacement cost, is the right measure for components with remaining life.
Capitalization of a rent differential converts an income difference into a price difference. If a comp’s rents exceed the subject’s by a measurable amount, calculate the annual difference. Divide that amount by a supported cap rate to estimate value impact. This is where the sales comparison approach borrows from the capitalization rate analysis that drives income valuation.
When quantitative support is thin, qualitative analysis is more honest than a fabricated percentage. Relative comparison ranks each comp as superior, similar, or inferior. Bracketing then places subject value between the best inferior comp and the worst superior comp. A defensible range beats a precise number built on invented adjustments.
Choosing the right unit of comparison
The unit of comparison should match how buyers in that market actually price the asset. Using the wrong one introduces distortion that no amount of adjusting will remove.
Office, retail, and industrial sales use price per square foot. Industrial buyers also check clear height, office finish ratio, and the area measure under ANSI/BOMA Z65. Price per unit governs multifamily and self-storage, with price per square foot serving as a cross-check on unit size. Land uses price per acre or per buildable square foot. Entitlement status and zoning density usually matter more than raw acreage. Price per key governs hospitality; price per bed governs seniors housing and student housing.
Scale effects run through nearly all of these units. Larger buildings trade at lower prices per square foot than smaller peers. The buyer pool narrows as check size grows. Land and site costs also spread across more area. That inverse relationship makes size adjustments move opposite to intuition. Wide differences in building size therefore require explicit correction in price-per-square-foot comparisons.
Reconciling comps into one value indication
Reconciliation is analysis, not arithmetic. Averaging the adjusted indications treats the weakest comp as equal to the strongest, which is the opposite of what the evidence supports.
Weight follows reliability, and reliability is measured two ways. Gross adjustment (the sum of all adjustments regardless of direction) measures how much the analyst had to intervene. A comp requiring heavy intervention is a weak comp even if the adjustments net to zero. Net adjustment measures directional bias. A comp with a small gross adjustment and verified transaction details carries more weight than a nearby sale that needed corrections on four dimensions.
The reconciled conclusion should sit inside the range of adjusted indications and cluster near the most reliable ones. Stating why (naming which comps drove the conclusion and which were treated as bracketing evidence) is what makes the number reviewable. In a broker opinion of value, that reasoning paragraph does more work than the spreadsheet behind it.
Where the approach loses reliability
Thin data is the primary constraint. Specialized assets (a regional mall, a cold storage facility, a purpose-built lab building) may have no local sales at all within a usable time window. Widening the geography or the date range trades one form of error for another.
Rapidly moving markets compound the problem. When pricing shifts quickly, the market conditions adjustment becomes the largest single correction in the grid. It is the hardest one to support with paired sales, since resales of the same property over a short interval are uncommon. A closed sale also reflects terms agreed weeks or months earlier, so recent closings can lag current conditions.
Income-producing property valued for investment presents a structural limitation. Two identical buildings with different tenants, lease terms, and escalations are not economically identical, and a physical-attribute grid will not capture that. Here, sales comparison checks the income conclusion for reasonableness. The cost approach performs the same role for new construction and special-purpose assets.
Worked example: a 10,000 SF retail strip
All figures below are illustrative and chosen for round arithmetic. They are not market data.
Subject: 10,000 SF multi-tenant retail strip, mid-block location, fully leased, no deferred maintenance.
| Comp A | Comp B | Comp C | |
|---|---|---|---|
| Building size | 12,000 SF | 8,000 SF | 11,000 SF |
| Sale price | $2,400,000 | $1,800,000 | $2,090,000 |
| Price per SF | $200 | $225 | $190 |
| Months before effective date | 12 | 3 | 6 |
Step 1, Market conditions. Applying an illustrative 2% annual rate derived from local resales: A becomes $204.00/SF, B becomes $226.13/SF, C becomes $191.90/SF.
Step 2, Location. Comp A sits on a secondary corridor with weaker traffic counts (+10%): $224.40/SF. Comp B occupies a signalized hard corner (−8%): $208.04/SF. Comp C is comparable (0%): $191.90/SF.
Step 3, Condition. Comp C needed a $110,000 roof the buyer replaced after closing, or $10/SF (+$10): $201.90/SF.
Step 4, Size. Larger buildings trade lower per square foot. Comp A adjusts up 3% to $231.13/SF, and Comp C adjusts up 1% to $203.92/SF. Smaller Comp B adjusts down 1% to $205.96/SF.
Result. Adjusted indications: A $231/SF, B $206/SF, C $204/SF. Gross adjustments: A 15%, B 9.5%, C 7.2%.
Interpretation. Comps B and C required the least intervention and land within $2/SF of each other. Comp A carries the largest gross adjustment, driven almost entirely by a location correction, and functions as the upper bracket rather than as primary evidence. Weighting B and C, the indicated value is roughly $205/SF, or $2,050,000.
A simple average produces $214/SF and a $2,140,000 conclusion. That is $90,000 higher because the least reliable comp received equal weight.
Common mistakes that get comps thrown out
- Adjusting in the wrong direction. Marking a superior comp upward instead of downward doubles the error. Every adjustment answers what the comp would have sold for as the subject.
- Treating recorded price as verified price. Unconfirmed sales hide seller financing, portfolio allocations, and related-party transfers, any of which can move the price well outside market. An unverified comp presented as evidence is the fastest route to a rejected valuation.
- Mismatching the property rights conveyed. Comparing a leased fee sale encumbered by a below-market lease to a fee simple subject imports the lease discount into the subject’s value without disclosure.
- Stacking unsupported percentage adjustments. Five judgment-based corrections of 5% each produce a 25% gross adjustment and a number no reviewer will accept. Fewer, better-supported comps beat more, heavily adjusted ones.
- Ignoring conditions of sale. A 1031 buyer under a deadline, an adjacent owner paying an assemblage premium, or a lender disposing of REO faces atypical motivation. Each requires an explicit adjustment or exclusion.
Lending, litigation, tax appeal, and financial-reporting valuations require a licensed or certified appraiser working under USPAP. Consult one before relying on comp analysis for those purposes.
Related terms
- Income approach to value
- Cost approach
- Capitalization rate
- Net operating income
- Highest and best use
- Broker opinion of value
- Price per square foot
Frequently asked questions
How many comparable sales are needed?
Three to six verified sales is typical practice, with the emphasis on verification rather than count. Three closely comparable, confirmed transactions support a stronger conclusion than eight loosely related ones. Fewer than three makes bracketing difficult, since the analyst cannot establish that the subject falls between superior and inferior evidence.
How old can a comparable sale be?
It depends on how well market conditions can be measured, not on a fixed window. A sale from two years ago is usable when resale data supports a defensible time adjustment. A six-month-old sale is questionable when pricing moved sharply and no evidence exists to quantify the shift.
How does the sales comparison approach differ from the income approach?
The sales comparison approach prices the asset by reference to what similar assets sold for. The income approach prices the cash flow the asset produces, usually by capitalizing net operating income or discounting projected cash flows. Owner-user and land valuations lean on the first; leased investment property leans on the second.
Can a broker opinion of value use this approach?
Yes, and most do. A broker opinion of value is not an appraisal and cannot substitute for one where an appraisal is legally required. However, it applies the same comparison logic. State licensing rules govern when a broker may prepare one and how it must be labeled.
What is bracketing?
Bracketing establishes that the subject’s value falls between a comp that is clearly inferior and one that is clearly superior. It is a qualitative technique used when paired-sales data is too thin to support dollar or percentage adjustments. It produces a defensible range rather than a point estimate.