How to Analyze a Rent Roll
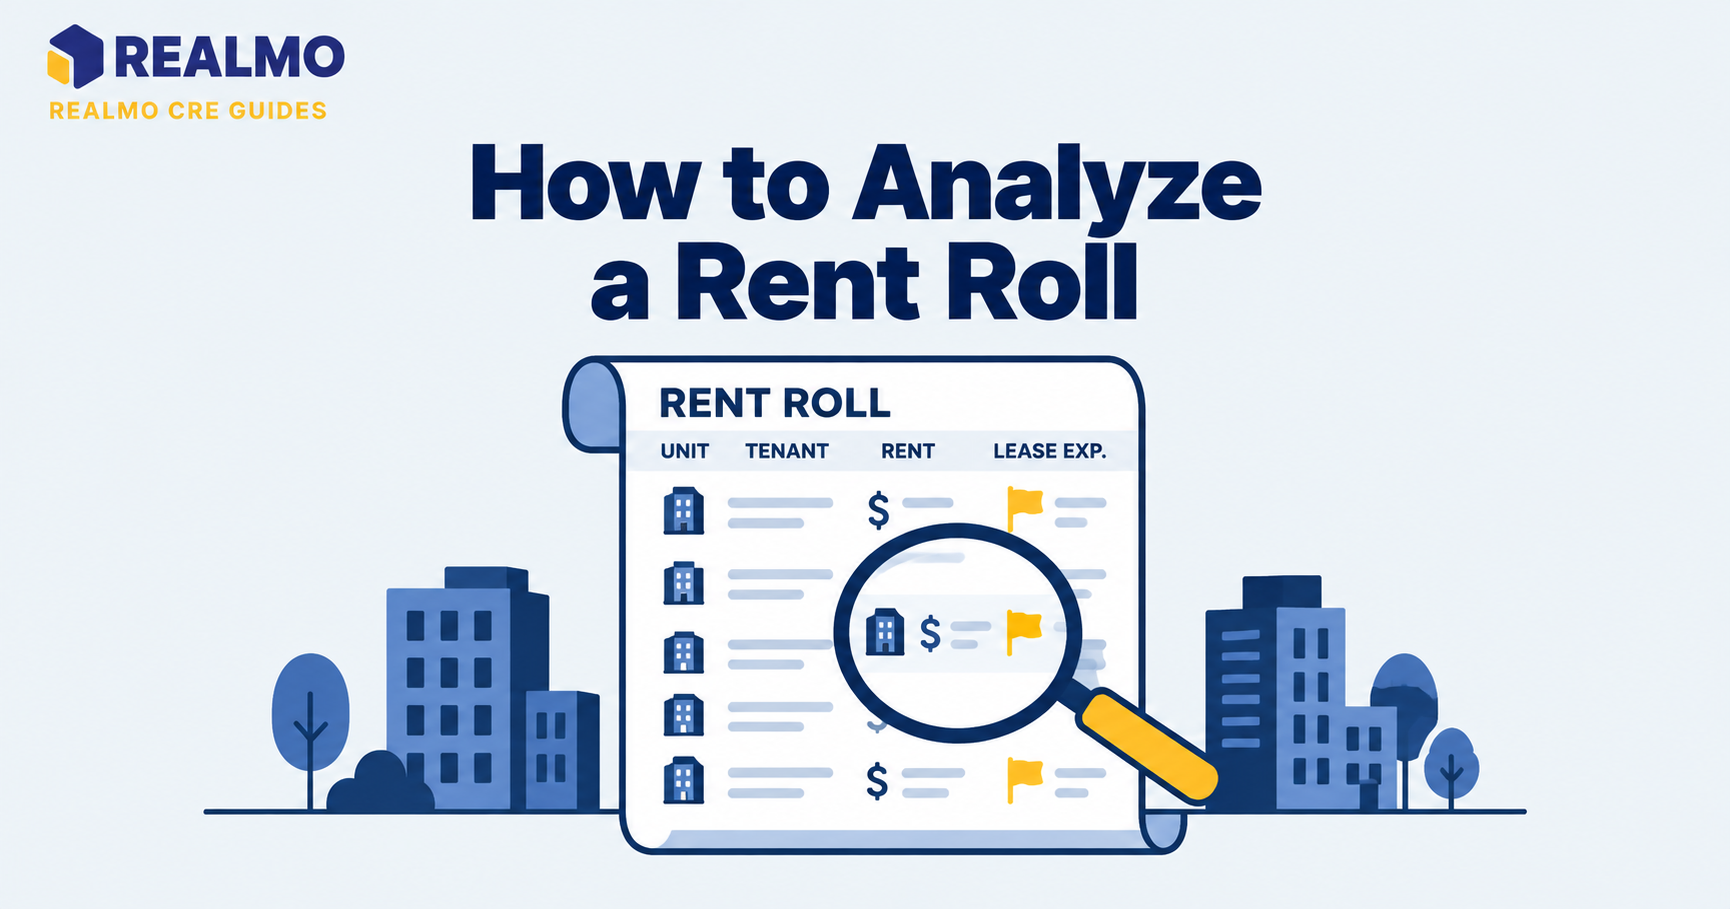
Rent roll analysis is the line-by-line review of a property’s tenant schedule to verify income, test lease quality, and expose risk that the offering memorandum smooths over. It converts a static rent list into a forward view of cash flow, rollover exposure, and negotiating leverage.
Why rent roll analysis decides the deal
A broker who reads the rent roll well controls the conversation. Take a 42,000-square-foot multi-tenant flex building brought to market by an owner who priced it off in-place net operating income. The summary page shows full occupancy and a clean income figure. The rent roll itself shows something different. Three of eleven leases expire within fourteen months, two tenants are paying rents set at the top of the last cycle. One lease has a free-rent period still running, and the largest tenant occupies 31% of the building on a lease with no renewal option.
That is four separate arguments about price, and every one of them came from a spreadsheet the seller handed over voluntarily. On the buy side, the same reading tells the client what the first two years of ownership actually look like. On the sell side, catching these items before a buyer does lets you frame them rather than defend them.
What a complete rent roll must contain
A usable rent roll carries, at minimum: unit or suite identifier, tenant legal name, leased square footage, lease commencement and expiration dates, current base rent stated both monthly and annually, rent per square foot, escalation schedule, security deposit, renewal and termination options, and the expense structure governing each lease.
Missing fields are information. A rent roll without expiration dates hides rollover. A rent roll without escalation terms hides flat leases that lose ground to inflation every year. A rent roll that reports only total monthly rent, with no square footage, prevents any comparison to market and should be treated as incomplete until the owner supplies the rest.
Watch for the difference between a rent roll and a rent ledger. The roll states what tenants are contractually obligated to pay. The ledger states what they actually paid. Analysis needs both, and the gap between them is the most valuable number in the file.
How to verify the rent roll against source documents
Never underwrite a rent roll on its own. It is a document the seller produced, in a format the seller chose, from data the seller entered.
Pull the lease abstracts and tie each line to its lease. Confirm the commencement date, the expiration date, the current rent step, the square footage, and any option language. Then tie the roll to the trailing twelve-month operating statement and to bank deposits where available. In-place rent that exceeds collected rent means concessions, delinquency, or both.
Square footage deserves particular scrutiny. Leases may be written under a different ANSI/BOMA Z65 measurement standard than the marketing materials use, and load factors applied to common areas can inflate rentable area above usable area. When rent per square foot looks unusually low for the submarket, remeasurement is frequently the reason rather than a below-market lease.
Reading lease expirations and rollover risk
Sort the roll by expiration date and total the square footage expiring in each of the next five years. This lease expiration schedule is the single most useful derivative of the rent roll.
Concentrated rollover is the risk. A property where 40% of the space expires in one year exposes the owner to a specific leasing market at a specific moment. Plus simultaneous demand for tenant improvement dollars and leasing commissions. Staggered expirations spread that exposure across cycles. Two buildings with identical current income can carry very different risk profiles for this reason alone, and the difference belongs in the cap rate discussion.
Also flag leases already holding over on a month-to-month basis. They inflate occupancy on paper while providing none of the term that lenders and buyers actually pay for.
Testing in-place rent against market rent
Every line on the roll should be marked as at, above, or below market. The comparison drives the entire value-add thesis.
Below-market leases represent embedded upside, but only upside a buyer can reach. A tenant twelve years into a fifteen-year lease with two five-year options at 95% of fair market. Rent may never roll to market in the holding period. Above-market leases create the reverse problem: income that disappears at expiration, and a seller who wants to be paid for it today.
Rather than quoting a market rent figure, build the comparison from current signed comparables in the submarket for similar space, then adjust for the expense structure. A gross lease and a triple-net lease at the same face rent are not the same economics, and comparing them directly is one of the fastest ways to misprice a building. Realmo’s Location Insights and property-level analytics can help establish the submarket baseline before you commit to a rent conclusion.
Evaluating tenant credit and concentration
Rank tenants by percentage of total income, not by square footage. A small suite paying premium rent can matter more than a large low-rent user.
Then assess who those tenants are. An investment-grade national credit, a regional operator with multiple locations, a franchisee, and a startup on its first lease all present different default probabilities, and lenders price them differently. Ask whether leases are guaranteed, and by whom , a corporate guaranty from a parent entity and a personal guaranty from an owner-operator carry different weight.
Concentration compounds credit risk. When one tenant occupies a large share of the building, a single business failure changes the asset from stabilized to distressed. Note whether that tenant’s space is generic or specialized, since specialized improvements narrow the pool of replacement tenants.
Worked example: converting a rent roll into a rollover picture
Illustrative figures only.
A ten-suite retail strip totals 20,000 rentable square feet. Four suites, totaling 8,000 square feet, expire within eighteen months. Combined base rent on those four suites is $200,000 per year, or $25 per square foot. Total property base rent is $460,000.
Step one: expiring share of income. $200,000 ÷ $460,000 = 43.5%.
Step two: expiring share of area. 8,000 ÷ 20,000 = 40%.
Step three: downtime and cost. Assume comparable spaces in the submarket lease in six months and require tenant improvement allowances and leasing commissions. Six months of vacancy on 8,000 square feet at $25 per square foot costs $100,000 in lost rent. Tenant improvement costs come on top of that.
Step four: interpretation. Nearly half the property’s income is exposed within eighteen months, and the cash requirement to re-tenant arrives at the same time. A buyer underwriting stabilized income here is underwriting a year that will not happen. The appropriate response is a rollover reserve in the model and a price adjustment, not a higher cap rate applied to unadjusted income.
Common error: treating the four expirations as independent. If all four sit in the same corridor and serve the same customer base, they may re-lease together or sit empty together. Correlation matters. See lease expiration schedules and tenant improvement allowances for the underlying mechanics.
Reconciling the rent roll with the operating statement
The rent roll and the trailing twelve-month statement must agree, and when they do not, the discrepancy is the finding.
Annualized in-place rent from the roll will normally exceed collected rental income on the operating statement. Legitimate causes include mid-year lease commencements, free rent periods, and vacancy that occurred during the trailing period. Illegitimate causes include chronic delinquency, side agreements reducing rent, and tenants who have quietly stopped paying while remaining on the roll.
Request an aged receivables report alongside the roll. A tenant ninety days past due is a vacancy the seller has not yet acknowledged. Compare recovery income on the statement to the expense structures shown on the roll as well; if leases are triple-net but recoveries fall well short of reimbursable expenses, either the leases have caps and exclusions the roll does not show, or the owner is not billing correctly.
Common mistakes in rent roll analysis
Accepting the summary page instead of the detail. Owner-prepared summaries report averages that conceal distribution. The consequence is underwriting a blended rent that no individual lease actually supports.
Ignoring options. Renewal options at fixed rents, expansion rights, termination rights, and rights of first refusal all constrain what an owner can do with the building. A termination option discovered after closing can eliminate the anchor income the purchase price was built on.
Treating occupancy as economic occupancy. Physical occupancy counts bodies in space. Economic occupancy counts rent actually collected. Free rent, abatements, and delinquency drive the two apart, and financing sized on the wrong one comes up short.
Skipping the expense structure per lease. In a building with mixed gross and net leases, applying one recovery assumption across all tenants misstates net operating income in both directions.
Failing to check whether escalations are contractual. Rent steps written into the lease are income. Rent increases the owner “expects” at renewal are assumptions, and they do not belong in year-one underwriting.
Related terms
Net operating income · Lease expiration schedule · Economic vacancy · Triple net lease · Weighted average lease term · Tenant improvement allowance · Estoppel certificate · Cap rate
FAQ
What is a rent roll in commercial real estate?
How do you verify a rent roll is accurate?
Tie each line to the underlying lease or lease abstract, then reconcile total in-place rent to the trailing twelve-month operating statement and bank deposits. Request an aged receivables report and tenant estoppel certificates, which have tenants confirm their own lease terms directly.
How do you verify a rent roll is accurate?
Tie each line to the underlying lease or lease abstract, then reconcile total in-place rent to the trailing twelve-month operating statement and bank deposits. Request an aged receivables report and tenant estoppel certificates, which have tenants confirm their own lease terms directly.
What is the difference between a rent roll and a lease abstract?
A rent roll summarizes all leases in one table for portfolio-level review. A lease abstract condenses one lease into its key provisions, including clauses a rent roll omits, such as assignment rights, exclusive use, and default remedies. Serious analysis uses both.
Why does economic occupancy differ from physical occupancy?
Physical occupancy measures space under lease. Economic occupancy measures rent actually collected against gross potential rent. Free rent periods, abatements, delinquency, and holdover tenants create the gap, and it is usually invisible on a rent roll alone.
What rollover concentration is considered risky?
There is no single threshold, and practitioners weigh it against lease term, tenant credit, and submarket depth. The common approach is to compare expiring square footage each year to total area. Then assess whether the local leasing market can absorb that space within the reserve period the model assumes.