Commercial Property Classes: A, B and C Explained
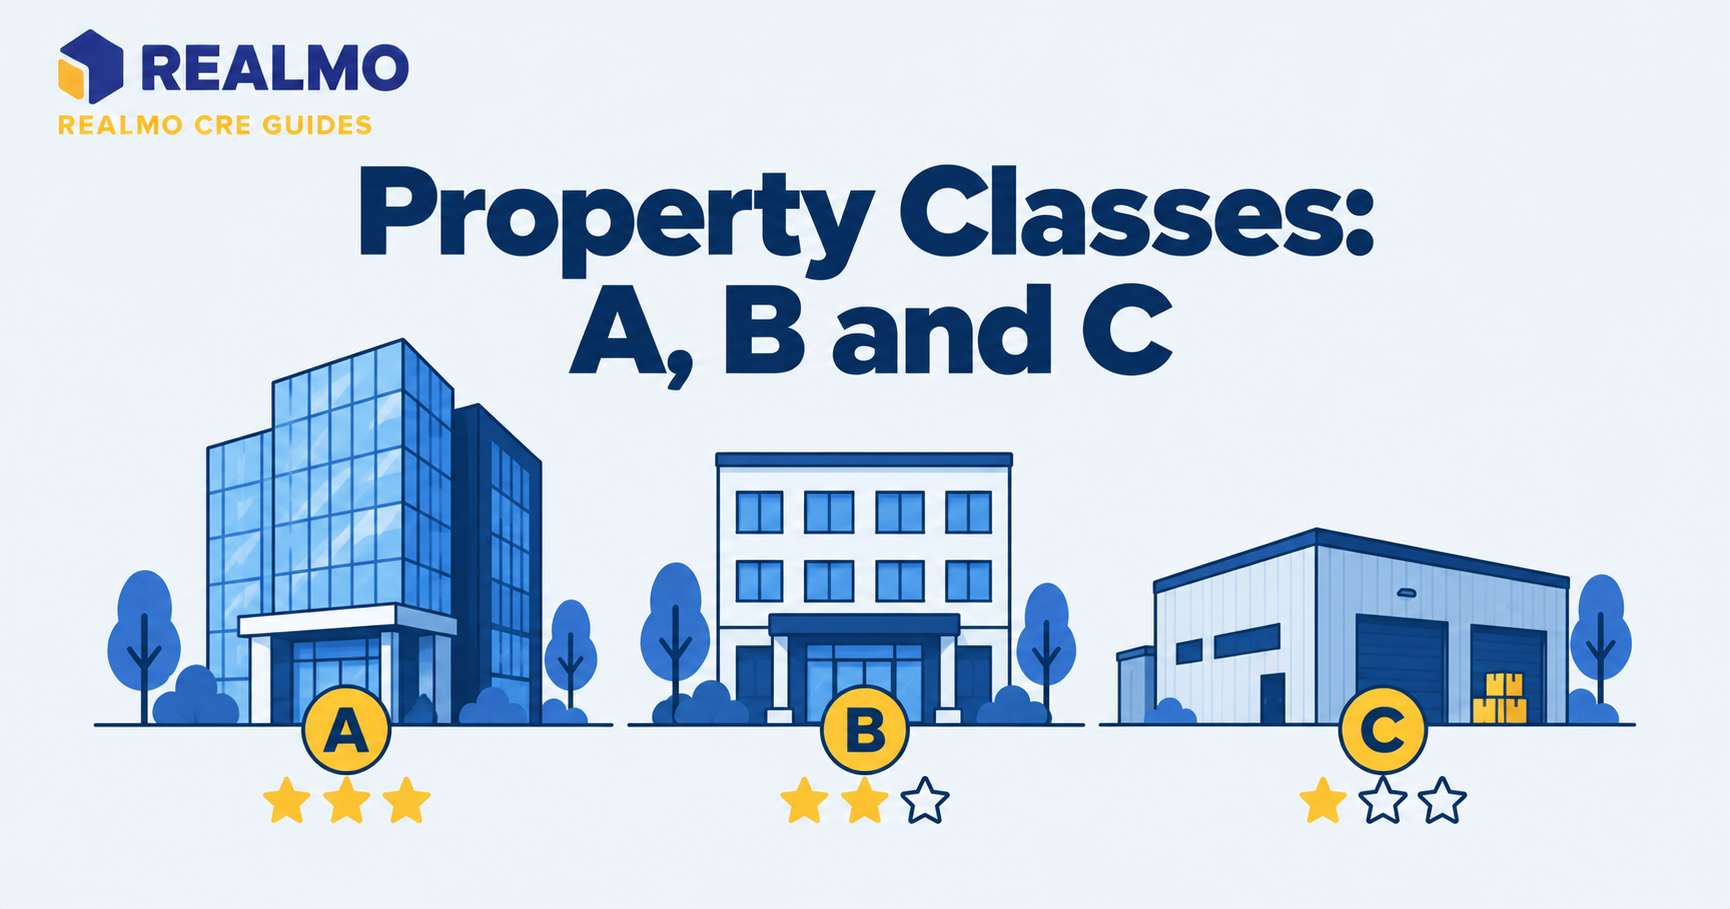
Property class is an informal grading system that sorts commercial buildings by age, construction quality, location, amenities, and the rents and tenants they command. Most commonly, that means Class A, B, and C office buildings. No agency assigns these grades. Brokers, appraisers, and lenders apply them by convention, and the meaning shifts from one market to the next.
Why Class Is the First Filter in Any Office Deal
An investor screening two 100,000-square-foot office buildings priced 60% apart is not looking at a bargain and a premium asset. They are looking at two different business plans. The Class A tower is a yield play with institutional tenants, long remaining lease terms, and modest near-term capital needs. The Class C building across town is a leasing and capital problem that happens to have a roof on it.
Class tells you, before you open a rent roll, roughly what your tenant credit looks like. It also signals how much you will spend on tenant improvements and leasing commissions per renewal, and how long space sits vacant between tenants. It tells you which lenders will quote the deal at all. Getting the class wrong at the screening stage means you carry a mispriced risk assumption through the entire underwriting model.
What Class A, B, and C Office Buildings Mean
Class A describes the top of a market. Buildings are newer or thoroughly modernized, with prime locations, efficient floor plates, structured parking, strong building systems, and professional institutional management. They command the highest achievable rents in that submarket. Tenants are usually national or credit-rated firms signing long leases.
Class B buildings are functional and well located but older, with dated finishes, less efficient mechanical systems, or fewer amenities. They lease to regional firms, professional services, and back-office users at meaningful discounts to Class A. Most value-add office strategies live here, because the gap between current and achievable rent is real but the bones are sound.
Class C buildings are older still, commonly decades past their last significant renovation, with deferred maintenance, obsolete layouts, weaker locations, or all three. They compete almost entirely on price. Some are redevelopment or adaptive reuse candidates rather than going concerns, and the land can be worth more than the improvements.
A fourth informal grade, Class D, appears occasionally for functionally obsolete or largely vacant buildings. It is not standardized and most brokers fold it into Class C.
Why the Same Building Can Be A in One Market, B in Another
Class is relative to the submarket, not to a national scale. A 1990s mid-rise with surface parking may be the best building in a secondary metro and trade as Class A there. Move the identical structure to a central business district with new towers and it reads as solid Class B.
This creates a recurring trap in comparable analysis. Pulling “Class A office” comps across metros compares grades that were assigned against different local benchmarks. Class is only useful when you hold geography constant: same submarket, ideally same competitive set. That is also why building class and submarket definition have to be established together, not sequentially.
Grades also drift. A building does not have to change for its class to fall. Enough new supply nearby will reset the benchmark and push yesterday’s Class A into Class B. Investors underwriting a long hold should assume the label degrades over time unless capital keeps pace.
How Class Shows Up in Rent, Vacancy, and Cap Rates
Rent stratification is the clearest signal. Class A commands the highest face rents in a submarket, Class B a discount, Class C a deeper one. The size of that spread is itself informative. A wide A-to-B rent gap usually points to a market where new construction has raised the amenity bar. A narrow gap suggests older stock is competing effectively on price and location.
Vacancy behaves differently by class across a cycle. In downturns, tenants with flexibility have historically traded up in quality at compressed rents. That pressures Class B and C occupancy, while Class A holds better than its rent levels alone would suggest. In recoveries, Class A absorbs first and pricing power returns there first.
Cap rates follow the same logic in reverse. Class A usually prices at lower cap rates than Class B or C in the same submarket, because cash flows are more durable. The reasons are longer weighted average lease terms, stronger tenant credit, lower re-leasing frequency, and less near-term capital expenditure. The spread between class tiers is a risk premium, not a discount waiting to be captured. When you see an unusually wide spread, ask which specific risk the market is pricing. It could be capital needs, tenant concentration, or a location that is slipping.
Property Class Beyond Office: Retail and Industrial
Class language originated with office and transfers imperfectly. In industrial property, the practical grading factors are clear height, dock-door ratio, column spacing, truck court depth, and power capacity. A 36-foot clear building with ample trailer parking functions as Class A, regardless of finish quality. A 22-foot clear 1980s box does not, however well maintained.
Retail is graded more by trade area, co-tenancy, and traffic counts than by building age. That’s why the sector leans on formats, like power center, neighborhood center, or strip, instead of letter grades. Multifamily uses A/B/C conventionally, with Class C commonly standing in for workforce housing.
The takeaway for an investor moving between property types: ask what the letter is actually measuring in that sector before importing assumptions from office.
Worked Example: Class A vs. Class B on the Same Block
All figures below are illustrative round numbers chosen to show the mechanics, not market quotes.
Two 100,000-square-foot office buildings sit on the same block. Building A is Class A: 90% leased at $40 per square foot full-service gross, operating expenses of $14 per square foot across the whole building. Building B is Class B: 80% leased at $28 per square foot, operating expenses of $12 per square foot.
Building A revenue: 90,000 × $40 = $3,600,000. Operating expenses: 100,000 × $14 = $1,400,000. NOI = $2,200,000. At an illustrative 6.0% cap rate, value is $36,670,000, or roughly $367 per square foot.
Building B revenue: 80,000 × $28 = $2,240,000. Operating expenses: 100,000 × $12 = $1,200,000. NOI = $1,040,000. At an illustrative 7.5% cap rate, value is $13,870,000, or roughly $139 per square foot.
How to read it: Building B trades at 38% of Building A’s per-foot value while producing 47% of the NOI. The 150-basis-point cap rate spread and the price gap together represent the market’s estimate of what Building B still owes. That includes releasing 20,000 vacant square feet, tenant improvement and leasing commission dollars on every rollover, and the capital to keep it competitive. The value-add case only works if your capital plan costs less than that discount.
The common error here is arithmetic in the wrong direction. It means renovating Building B, applying Class A rents to the pro forma, and then also applying the Class A cap rate on exit. A Class B building in a Class B location rarely earns both.
Common Mistakes When Reading a Property Class
- Treating the class in a marketing flyer as verified. Brokers grade generously. If the building’s actual finishes, systems, and rent achievement say B, underwriting it as A overstates exit value and rent growth. That gap usually runs more than the entire equity margin.
- Comparing classes across markets. Class A comps from a different metro embed a different local benchmark and will misprice your deal in either direction.
- Assuming class can be bought with renovation. Capital fixes finishes, lobbies, and some systems. It does not fix floor plate depth, ceiling height, column spacing, parking ratio, or location, and those are frequently what caps the grade.
- Ignoring the age of the class assignment. New supply in the submarket resets the standard; a grade assigned five years ago may no longer hold.
- Forgetting that class drives financing. Lender appetite, proceeds, and structure differ sharply by tier. A Class C acquisition financed on Class B assumptions can fail at the term sheet stage.
When you are checking a class claim, pull the building’s actual attributes: year built, renovation history, ownership, and current use. Compare those against similar properties in the same submarket. Realmo’s property analytics cover ownership records, valuation, and location context across 9M+ properties, which is usually faster than reconstructing a competitive set from listing sheets.
FAQs
Who decides whether a building is Class A, B, or C?
No one officially. Brokers, appraisers, lenders, and research firms apply the grades by convention, using local benchmarks. BOMA International publishes widely referenced descriptive guidance, but it is not a certification. Two credible professionals can reasonably grade the same building differently, which is why the underlying attributes matter more than the letter.
Can a Class C building be upgraded to Class A?
Rarely through renovation alone. Finishes, lobbies, elevators, and building systems can be replaced, but floor plate geometry, ceiling height, parking, and location usually cannot. Buildings that make the full jump usually do so through gut redevelopment or a change of use, priced as ground-up projects rather than improvements.
Do Class A properties always produce better returns?
No. Class A usually offers more stable cash flow at lower going-in yields, while lower-tier assets offer higher yields against greater releasing and capital risk. Which produces better risk-adjusted returns depends on the specific asset, business plan, and holding period, not on the letter grade.
Is property class the same as building quality rating in an appraisal?
Not identical. Appraisers use quality and condition ratings tied to construction and maintenance, while class blends those with location, amenities, tenancy, and market position. A well-maintained building in a weak location can rate high on condition and still be Class C.
Related terms: Cap rate · Net operating income · Value-add investing · Tenant improvement allowance · Weighted average lease term · Submarket analysis · Functional obsolescence · Replacement cost