Who’s Who in a CRE Deal: Roles Explained
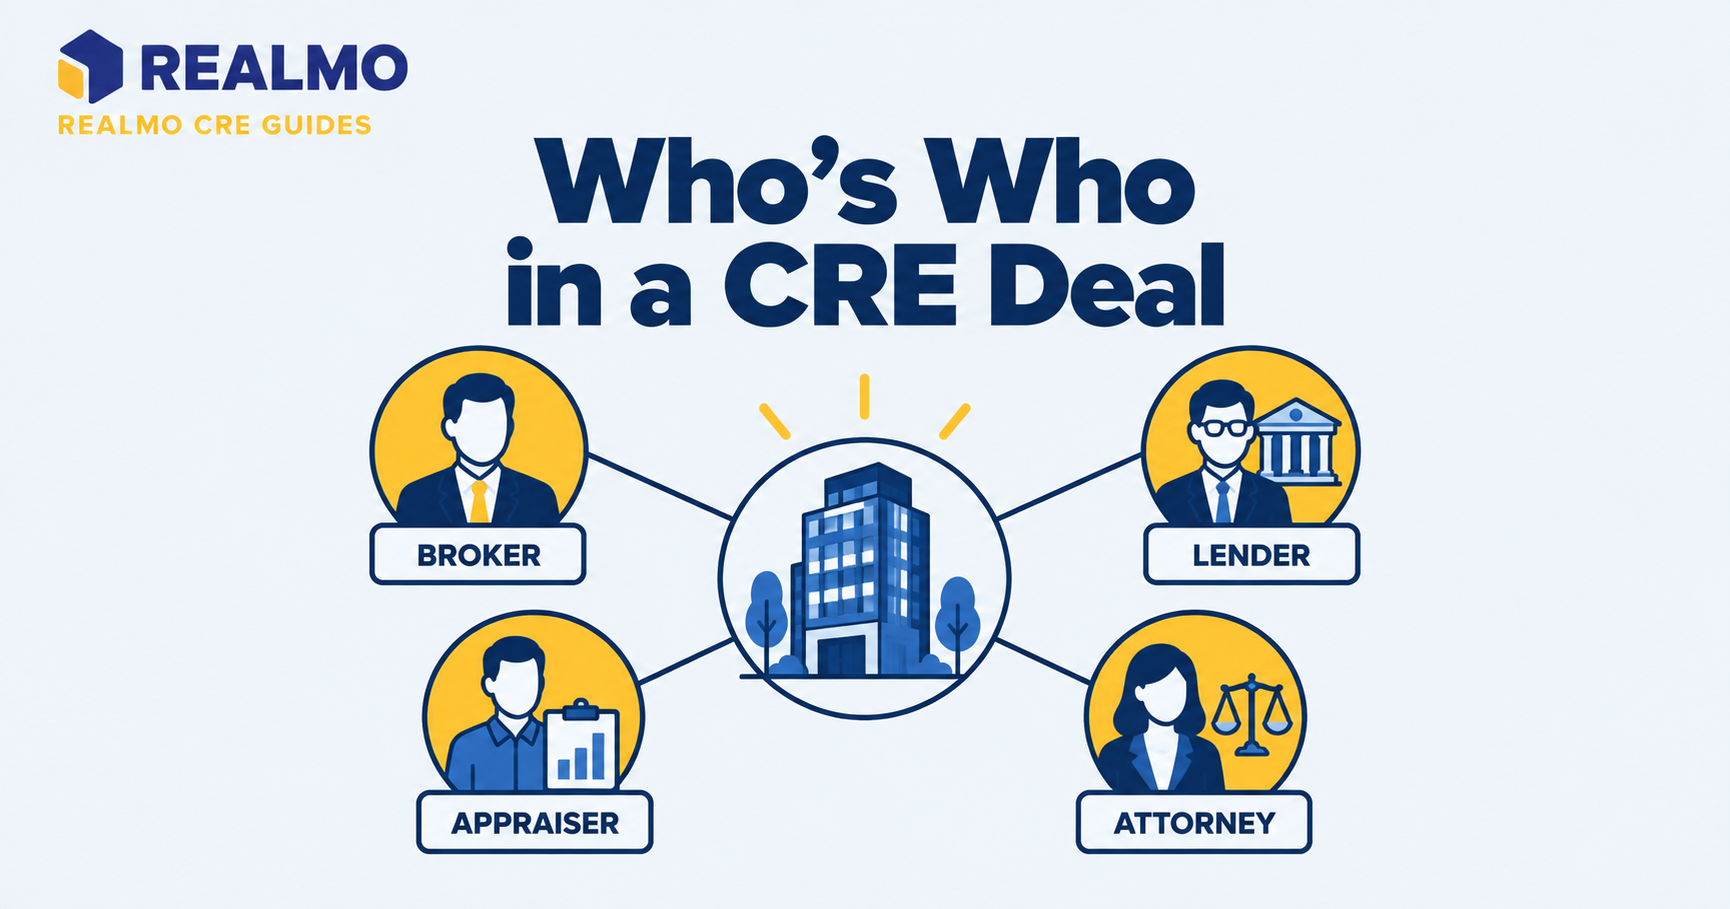
Commercial real estate roles are specialized functions: broker, lender, attorney, appraiser, title officer, property manager, and others. Each one carries a defined piece of a transaction. A single deal involves eight to fifteen of them. Knowing who owns which decision determines how fast the deal closes, and who absorbs the cost when something breaks.
Why knowing the roles changes your first deal
You’re buying a $2.8 million flex industrial building. Three weeks into diligence, the survey turns up a driveway easement the seller’s marketing package never mentioned. The listing broker won’t flag it: they represent the seller. The lender won’t either; they’ll just reprice or walk away. The title company catches the exception. Your attorney decides whether it blocks the loading dock access your future tenant needs. Your broker then renegotiates price or demands a cure before closing.
Investors who don’t know the map default to asking whoever answers the phone. That usually means asking a broker for legal advice, or a lender for valuation guidance. Neither is licensed or incentivized to answer well. The cost shows up as a missed contingency deadline, a repriced loan, or an easement you discover after you own it.
The two sides: who represents the buyer and the seller
Every commercial transaction has a principal on each side and an agent orbiting each principal. The buyer (or tenant, in a lease) and the seller (or landlord) are the principals: they sign, they fund, they carry the risk.
A listing broker works for the seller under a listing agreement. That broker owes fiduciary duty to the seller: loyalty, confidentiality, and full disclosure of anything material to the seller’s interest. A buyer’s representative owes the same duties to the buyer. In many states a single broker can represent both sides as a dual agent or transaction broker. When that happens, the fiduciary duties collapse: the agent can no longer advocate on price for either party. State rules on disclosure and consent vary considerably, so confirm the agency status in writing before you share your walk-away number.
The commission is usually paid by the seller out of closing proceeds and split between the two brokerages. That structure means the buyer’s representative is compensated by the seller’s money, which some investors find uncomfortable and others accept as market convention. Either way, it’s a good reason to read the commission and fee structures before signing a representation agreement.
What a CRE broker actually does beyond finding the deal
Brokers source off-market inventory, build the offering memorandum, and run the bid process. On the buy side, they also assemble comparable sales, verify rent rolls against the offering package, and coordinate the calendar of contingency deadlines. Institutional-grade brokers underwrite the deal independently rather than accepting the seller’s proforma.
A broker isn’t licensed to give legal advice. Nor can they render a formal opinion of value in place of an appraisal, or advise on tax treatment. Brokers hold state real estate licenses, though the specific title varies by state. The pool includes generalists and specialists who work a single asset class in a single submarket. Asset-class specialization matters more than firm brand for anything below institutional scale. The person who has leased eleven multi-tenant industrial parks in your submarket knows what the rent roll will actually renew at.
Who underwrites the money: lenders, brokers, and servicers
The loan officer or relationship manager originates the loan and pitches it internally. The credit analyst or underwriter decides whether it clears the institution’s credit box, testing debt service coverage, loan-to-value, and sponsor liquidity. These are different people with different incentives: the originator is paid on volume, the underwriter on portfolio performance. A verbal indication from an originator is not a commitment.
A mortgage broker or debt broker shops the deal across multiple lenders and is paid a fee at closing. They earn their keep on complex or non-conforming deals: bridge financing, value-add business plans, borrowers without local banking relationships. For a straightforward stabilized acquisition with an existing bank relationship, the fee usually isn’t worth it.
After closing, a loan servicer collects payments and administers reserves and escrows. For securitized debt, the servicer (not the original lender) is who you call about a lease approval or an early payoff. Their discretion is limited by the pooling and servicing agreement (PSA). This is one of the most consistently underestimated frictions in commercial mortgage-backed securities (CMBS) and securitized lending.
Diligence roles: appraiser, engineer, environmental consultant, surveyor
The appraiser is engaged by the lender, not the buyer, even though the buyer usually pays. That distinction matters: the appraisal serves the lender’s collateral test, and a low appraisal reduces loan proceeds rather than automatically repricing the purchase. Appraisers are separately licensed and work under USPAP, the Uniform Standards of Professional Appraisal Practice; a broker’s opinion of value is not a substitute.
A property condition assessment by an engineering firm inventories roof, structure, HVAC, and paving, and produces a schedule of immediate repairs and long-term replacement reserves. That schedule feeds directly into your capital budget and usually into lender-required reserves.
The environmental consultant performs a Phase I Environmental Site Assessment: a records and site review, not sampling. Completing it under ASTM E1527 establishes the innocent landowner and bona fide prospective purchaser protections under CERCLA. Skipping it doesn’t just leave you uninformed: it forfeits a statutory defense. If the Phase I identifies a recognized environmental condition, a Phase II with sampling follows. The surveyor produces the ALTA/NSPS survey showing boundaries, easements, encroachments, and setbacks, which the title company relies on to remove the standard survey exception.
Closing roles: title, escrow, and attorneys
The title company searches the chain of ownership, issues a commitment listing exceptions, and after closing issues an ALTA title insurance policy insuring against defects. The escrow agent (sometimes the same firm, sometimes not) holds deposit funds and disburses at closing according to written instructions.
The transaction attorney drafts and negotiates the purchase and sale agreement, reviews title exceptions and estoppel certificates, and handles entity formation for the acquiring vehicle. In roughly half of U.S. states, attorney involvement at closing is customary or required. In the rest, title companies handle most of the mechanics, and attorney use is discretionary. Below a certain deal size, some investors skip counsel entirely. That’s a reasonable economic decision on a simple single-tenant purchase, and a costly one on anything with assumed debt, ground leases, or complex lease structures.
Post-closing roles: property manager, asset manager, leasing agent
These three get conflated constantly. The property manager runs day-to-day operations: rent collection, vendor contracts, maintenance, tenant requests, and monthly reporting. Compensation is usually a percentage of collected revenue.
The asset manager owns the business plan: hold period, capital deployment, refinance timing, disposition. On small portfolios the investor is the asset manager. On institutional portfolios it’s a dedicated professional whose decisions the property manager executes.
The leasing agent fills vacancy and is paid a leasing commission per executed lease. Some property management firms bundle leasing. Separating it can sharpen accountability: a bundled manager has less pressure to fill space quickly than a specialist paid only on signed leases.
Worked example: mapping roles on a $3M retail acquisition
Illustrative figures, chosen for round numbers rather than current market conditions.
Setup: A four-tenant strip retail center, $3,000,000 purchase price, 65% loan-to-value from a regional bank, 45-day diligence period.
Roles engaged and who pays:
| Role | Engaged by | Paid by |
|---|---|---|
| Listing broker | Seller | Seller (commission) |
| Buyer’s representative | Buyer | Seller (commission split) |
| Bank loan officer / underwriter | Buyer | Buyer (loan fees) |
| Appraiser | Lender | Buyer |
| Environmental consultant | Buyer or lender | Buyer |
| Property condition engineer | Buyer | Buyer |
| Surveyor | Buyer | Buyer |
| Title / escrow | Buyer | Split per contract |
| Buyer’s attorney | Buyer | Buyer |
| Property manager | Buyer | Buyer (post-closing) |
How it sequences: The buyer’s representative negotiates the purchase agreement, and the attorney papers it. Day 1 of diligence, the buyer orders survey, Phase I, and property condition assessment while the lender orders the appraisal. Estoppel certificates go out to all four tenants through the seller’s broker. Around day 30 the title commitment and survey arrive together; the attorney reviews exceptions against the survey. Around day 35 the appraisal returns.
Interpretation: The appraisal comes in at $2,880,000. The loan sizes to 65% of the lesser of price or value: $1,872,000 rather than $1,950,000. The buyer must cover $78,000 more in equity, renegotiate price, or terminate. The lender didn’t cause this and won’t fix it; the buyer’s representative and attorney handle the price conversation.
Common error: Ordering third-party reports on day 25 instead of day 1. Appraisals and environmental reports have turnaround times measured in weeks, and a diligence deadline expires whether or not the reports arrived. Order everything the first week.
Common mistakes investors make with deal roles
- Treating the listing broker as neutral. The listing broker’s fiduciary duty runs to the seller. Anything you disclose about your maximum price or financing fragility can legally be shared with their client. Consequence: you bid against yourself.
- Asking the wrong professional a licensed question. Brokers can’t give legal advice, lenders can’t advise on tax structuring, and appraisers can’t tell you whether the deal is good. Consequence: you act on an answer nobody is accountable for.
- Assuming the appraisal protects you. It measures collateral value for the lender, not whether the price is right for your business plan. Consequence: you mistake a clean appraisal for validation of your underwriting.
- Skipping the survey to save a few thousand dollars. Without it, the title policy keeps a standard survey exception, leaving encroachments and easements uninsured. Consequence: an uninsurable defect surfaces on your exit, at your expense.
- Hiring a property manager before writing the business plan. The manager executes; they don’t set strategy. Consequence: operations run competently toward no particular objective.
Related terms
Fiduciary duty in real estate agency · Debt service coverage ratio · Phase I Environmental Site Assessment · Estoppel certificate · ALTA survey · Property management fee structures · Letter of intent
Realmo’s broker directory lets you filter representatives by asset class and submarket before you have a deal under contract. That’s the point at which choosing the right one still matters.
FAQs
Do I need my own broker as a buyer in commercial real estate?
Not legally, but without one you’re negotiating against a professional whose duty runs to the seller. Buyer representation is commonly paid from the seller’s commission, so the direct cost to you is usually zero. The exception is off-market direct-to-owner deals where no commission pool exists.
Who pays for the appraisal in a commercial deal?
The buyer almost always pays, but the lender engages the appraiser and is the client. This preserves appraiser independence from the party with a financial interest in a high number. You may receive a copy, but you can’t direct the scope or dispute the conclusion the way a client could.
What’s the difference between a property manager and an asset manager?
The property manager handles daily operations (rent, maintenance, vendors, tenant relations) and is paid a percentage of collected revenue. The asset manager sets strategy: hold period, capital spending, refinancing, and sale timing. Small investors act as their own asset manager while outsourcing property management.
Can one broker represent both buyer and seller?
In many states, yes, as a dual agent or transaction broker, with written consent. Fiduciary advocacy on price disappears for both parties: the broker becomes a facilitator. Rules and required disclosures differ meaningfully by state, so verify locally before consenting.
When do I need a real estate attorney versus just a title company?
Some states require or customarily use attorney involvement at closing; others rely on title companies. Independent of state practice, retain counsel when the deal involves assumed debt, ground leases, joint venture equity, entity formation, or non-standard lease provisions.