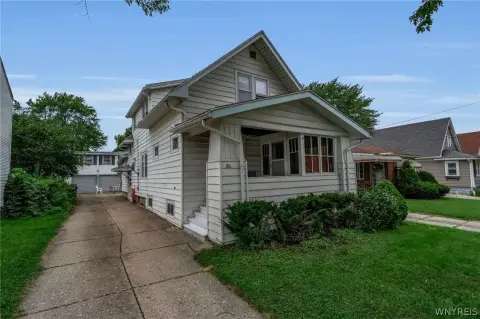
Renovated Multifamily
For Sale
$199,900
898 Northland Avenue, Buffalo, NY 14215
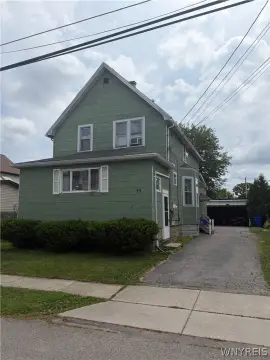
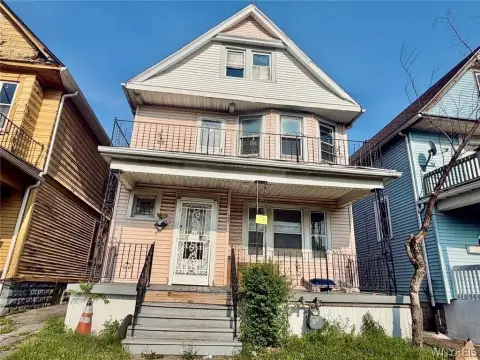
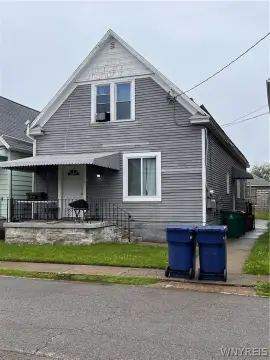
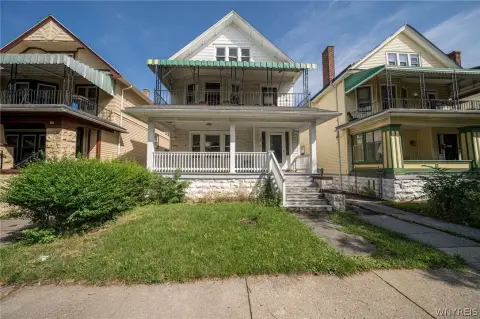
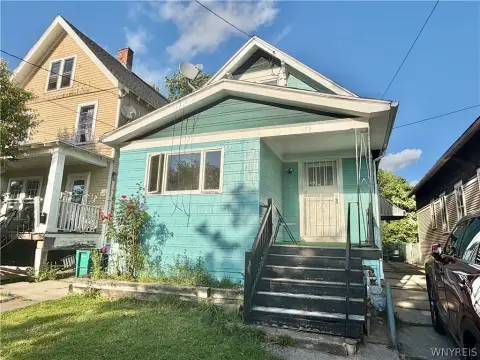
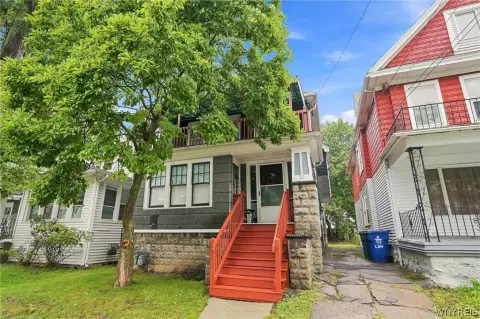
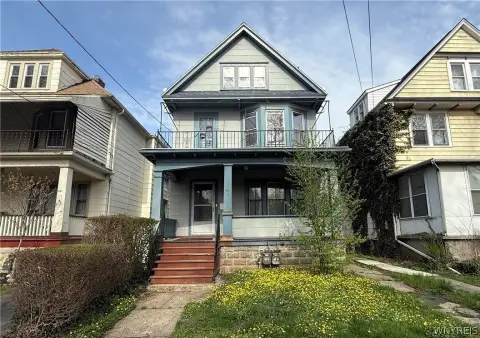
Updated interiors feature new vinyl flooring, a modernized kitchen, upgraded bathrooms, and flexible supplemental living areas.
Property Size1,977 SF
Days on Market22
Property Features for 898 Northland Avenue
General Information
Standard status
Active
Size
1,977 SF
Property subtype
Multi Family
Taxes and HOA fees
Annual Taxes
$1,213
Building Details
Building Size
1,977 SF
Year Built
1920
Listing Agency:
Keller Williams Realty WNY
Listed By:
MD Zahid Al Mamun · License #10401401589
(347) 357-4253
Source:
Highfallssir
Added: Sep 14
Changed: Sep 29
Last Checked: Oct 4 at 3:48PM
Displayed information is deemed reliable but is not guaranteed and should be independently verified. All listing content including descriptions, pricing, images are the copyrighted material of Keller Williams Realty WNY
Investment Insights
Based on property information with market context.
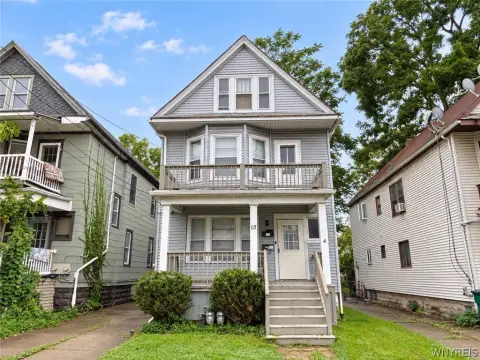
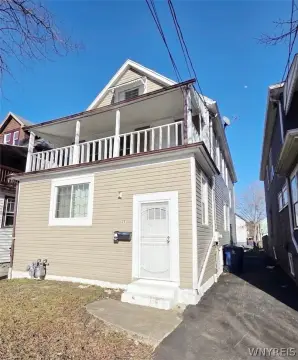
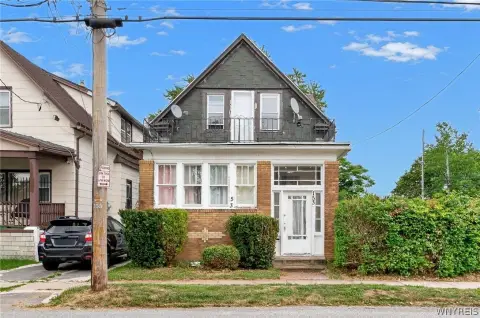
This renovated multifamily property provides 1,977 sq. ft. with five bedrooms and two upgraded bathrooms. Interior improvements include fresh paint, new vinyl flooring throughout, a modernized kitchen, and refreshed bathroom finishes. A bonus area with four rooms and a living space adds flexibility for additional household use or future apartment conversion as described in the property information.
The finished basement and full attic provide substantial additional interior space for storage, recreation, or other uses. Outside, the property includes a long driveway and a large backyard. The home was built in 1920 and is located near local supermarkets and community centers in Buffalo, New York.
The finished basement and full attic provide substantial additional interior space for storage, recreation, or other uses. Outside, the property includes a long driveway and a large backyard. The home was built in 1920 and is located near local supermarkets and community centers in Buffalo, New York.
Key Highlights
- 1,977 sq. ft. multifamily property
- Five bedrooms and 2 upgraded bathrooms
- Bonus area includes 4 rooms and a living space
Financial Insights
Estimated NOI and Cap Rate
NOI = area × lease_rate × (100 − vacancy) / 100 × (1 − expense_ratio). Net Operating Income — what the owner takes home each year before mortgage payments and income tax. Effective rent (asking rent minus vacancy losses) minus operating costs (taxes, insurance, maintenance, management).
NOI / Yr
$18,068
Cap rate = NOI / list price × 100. Capitalization rate — annual return on a fully cash purchase, before financing. NOI divided by price. Higher means more income per dollar invested, but usually also more risk or older condition. 5–8% is typical for stabilized commercial property; double digits often signal distressed deals.
Cap Rate
9.04%
Suggested Prices Based on Cap Rates
Cap rates vary significantly by property type, market, and asset quality.
Typical U.S. stable-market ranges:
Multifamily — 4.5% to 6.5% (Class A in primary markets often sub-5%; Class C in secondary markets 6%+)
Industrial / Logistics — 5.0% to 7.0% (compressed heavily in recent years due to e-commerce demand)
Office — 6.5% to 9%+ (wide spread post-2020; CBD Class A vs. suburban Class B varies dramatically)
Retail — 5.5% to 8.5% (grocery-anchored on the low end, unanchored strip centers higher)
Hospitality / Hotels — 7.5% to 10%+ (higher due to operational risk)
Self-Storage — 5.5% to 7.5%
Medical Office — 6.0% to 7.5%
Net Lease (single tenant, credit) — 5.0% to 7.0% depending on tenant credit and lease term
Rules of thumb:
Primary markets (NYC, SF, LA, Boston, DC) trade at lower cap rates than secondary/tertiary markets, often by 100–200 bps (bps, aka basis points; 1 bp = 0.01%).
Class A assets trade ~50–150 bps tighter than Class B, and Class B tighter than Class C.
Cap rates move inversely with price — a lower cap rate means a higher price for the same NOI.
Spread to the 10-year Treasury is a common benchmark; historically 200–400 bps over the 10-year.
Cap Rate 5%
$361,360
$361.4K
Cap Rate 7%
$258,114
$258.1K
Cap Rate 9%
$200,756
$200.8K
Market Conditions
NOI Build-Up for 1,977 SF
Vacancy — income lost from leasable area expected to sit empty during the year, subtracted from gross rent.
EGI (Effective Gross Income) — gross rent minus vacancy losses, the realistic income before paying operating costs.
OpEx (Operating Expenses) — recurring costs to operate the property (property tax, insurance, utilities, maintenance, management); excludes financing and capital improvements.
NOI (Net Operating Income) — income a property generates after operating costs but before financing and taxes.
Gross rent
$34.4K $17.40/SF
− Vacancy
−$1.5K −$0.78/SF
EGI
$32.9K $16.62/SF
− OpEx
−$14.8K −$7.48/SF
NOI
$18.1K $9.14/SF
Area
Buffalo, NY
Vacancy
4.50%
Lease Rate
$17.40 /SF/Yr
Expense Ratio
45.00%
Simulate Cap Rate and NOI
Suggested Prices Based on Cap Rates
Cap rates vary significantly by property type, market, and asset quality.
Typical U.S. stable-market ranges:
Multifamily — 4.5% to 6.5% (Class A in primary markets often sub-5%; Class C in secondary markets 6%+)
Industrial / Logistics — 5.0% to 7.0% (compressed heavily in recent years due to e-commerce demand)
Office — 6.5% to 9%+ (wide spread post-2020; CBD Class A vs. suburban Class B varies dramatically)
Retail — 5.5% to 8.5% (grocery-anchored on the low end, unanchored strip centers higher)
Hospitality / Hotels — 7.5% to 10%+ (higher due to operational risk)
Self-Storage — 5.5% to 7.5%
Medical Office — 6.0% to 7.5%
Net Lease (single tenant, credit) — 5.0% to 7.0% depending on tenant credit and lease term
Rules of thumb:
Primary markets (NYC, SF, LA, Boston, DC) trade at lower cap rates than secondary/tertiary markets, often by 100–200 bps (bps, aka basis points; 1 bp = 0.01%).
Class A assets trade ~50–150 bps tighter than Class B, and Class B tighter than Class C.
Cap rates move inversely with price — a lower cap rate means a higher price for the same NOI.
Spread to the 10-year Treasury is a common benchmark; historically 200–400 bps over the 10-year.
Cap Rate 5%
$361,360
Cap Rate 7%
$258,114
Cap Rate 9%
$200,756
Alternative Uses
Best Use
Apartment 5plus
$258.1K
$225.9K – $301.1K
NOI $18,068 @ 7.0% cap · market cap 9.04%
Second Best
—
—
no second resolved use
Theoretical Best
Office A
$475.4K
$416.0K – $554.7K
NOI $33,280 @ 7.0% cap · market cap 16.65%
Zoning and permitted uses should be independently verified with authorities.
Property Analytics
Unlock full access to Insights
Subscribe to Realmo Intelligence
Open Analytics
Current Use
Location Intelligence
Trade Area within ½ mile
977
Businesses Nearby
Explore this area
Business Placement
Demographics for 14215, NY
42,447
Population
19,203
Households
2.2
Avg Household Size
33
Median Age
19%
College-Educated
87%
High-School Grad
4.8 sq mi
ZIP Area
8,843
Density / Sq Mi
$43,326
Median Household Income
$29,204
Median Earnings
$993
Median Rent
$102,800
Median Home Value
Check the figures for this property
Cap Rate, Value Estimation, Potential NOI and more
View Realmo Analytics
Market
Vacancy Rate% for Multifamily in Northeast region
Questions? Ask Rey
Realmo’s AI knows this listing — price, zoning, demand, history. Ask anything.

Frequently Asked Questions
What type of property is this?
Multifamily property - Updated interiors feature new vinyl flooring, a modernized kitchen, upgraded bathrooms, and flexible supplemental living areas.
Where is this multifamily property located?
The property is located at 898 Northland Avenue Buffalo, NY.
What is the asking price?
The asking price for this property is $199,900.
What are key features of this property?
This property features: 1,977 sq. ft. multifamily property; Five bedrooms and 2 upgraded bathrooms; Bonus area includes 4 rooms and a living space