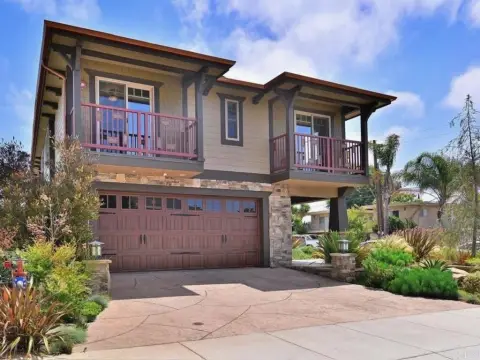
Freestanding Office
For Sale
Contact for pricing
845 Otay Lakes Rd, Chula Vista, CA 91913
R-1-zoned property with on-site parking and access from Otay Lakes Road.
Property Size3,200 SF
Price / SF$500
Days on Market36
Property Features for 845 Otay Lakes Rd
General Information
Standard status
Active
Size
3,200 SF
Total Parking Spaces
42
Property subtype
OFFICE
Zoning
R-1
Additional Details
Road Access
Yes
Building Details
Buildings
1
Listing Agency:
CBRE | San Diego
(858) 546-4600
Listed By:
Joe Yetter · License #00947371
(858) 775-3214
Source:
Moodyscre
Added: Aug 12
Changed: Sep 15
Last Checked: Sep 15 at 10:14AM
Displayed information is deemed reliable but is not guaranteed and should be independently verified. All listing content including descriptions, pricing, images are the copyrighted material of CBRE | San Diego
Investment Insights
Based on property information with market context.
This freestanding office building contains 3,200 square feet and is positioned on Otay Lakes Road in Eastern Chula Vista. The property is zoned R-1, with potential uses identified as including a church, school, or nursing home.
The building is across from Southwestern College, which has total enrollment of approximately 16,000. On-site parking includes approximately 42 spaces. Access is provided from Otay Lakes Road, with shared parking rights required by the neighboring Church.
The building is across from Southwestern College, which has total enrollment of approximately 16,000. On-site parking includes approximately 42 spaces. Access is provided from Otay Lakes Road, with shared parking rights required by the neighboring Church.
Key Highlights
- 3,200‑square‑foot freestanding office building
- R‑1 zoning with potential church, school, and nursing home uses identified
- Approximately 42 on‑site parking spaces
Financial Insights
Estimated NOI and Cap Rate
NOI = area × lease_rate × (100 − vacancy) / 100 × (1 − expense_ratio). Net Operating Income — what the owner takes home each year before mortgage payments and income tax. Effective rent (asking rent minus vacancy losses) minus operating costs (taxes, insurance, maintenance, management).
NOI / Yr
$53,622
Cap rate = NOI / list price × 100. Capitalization rate — annual return on a fully cash purchase, before financing. NOI divided by price. Higher means more income per dollar invested, but usually also more risk or older condition. 5–8% is typical for stabilized commercial property; double digits often signal distressed deals.
Cap Rate
3.35%
Suggested Prices Based on Cap Rates
Cap rates vary significantly by property type, market, and asset quality.
Typical U.S. stable-market ranges:
Multifamily — 4.5% to 6.5% (Class A in primary markets often sub-5%; Class C in secondary markets 6%+)
Industrial / Logistics — 5.0% to 7.0% (compressed heavily in recent years due to e-commerce demand)
Office — 6.5% to 9%+ (wide spread post-2020; CBD Class A vs. suburban Class B varies dramatically)
Retail — 5.5% to 8.5% (grocery-anchored on the low end, unanchored strip centers higher)
Hospitality / Hotels — 7.5% to 10%+ (higher due to operational risk)
Self-Storage — 5.5% to 7.5%
Medical Office — 6.0% to 7.5%
Net Lease (single tenant, credit) — 5.0% to 7.0% depending on tenant credit and lease term
Rules of thumb:
Primary markets (NYC, SF, LA, Boston, DC) trade at lower cap rates than secondary/tertiary markets, often by 100–200 bps (bps, aka basis points; 1 bp = 0.01%).
Class A assets trade ~50–150 bps tighter than Class B, and Class B tighter than Class C.
Cap rates move inversely with price — a lower cap rate means a higher price for the same NOI.
Spread to the 10-year Treasury is a common benchmark; historically 200–400 bps over the 10-year.
Cap Rate 5%
$1,072,440
$1.1M
Cap Rate 7%
$766,029
$766.0K
Cap Rate 9%
$595,800
$595.8K
Market Conditions
NOI Build-Up for 3,200 SF
Vacancy — income lost from leasable area expected to sit empty during the year, subtracted from gross rent.
EGI (Effective Gross Income) — gross rent minus vacancy losses, the realistic income before paying operating costs.
OpEx (Operating Expenses) — recurring costs to operate the property (property tax, insurance, utilities, maintenance, management); excludes financing and capital improvements.
NOI (Net Operating Income) — income a property generates after operating costs but before financing and taxes.
Gross rent
$83.3K $26.04/SF
− Vacancy
−$11.8K −$3.70/SF
EGI
$71.5K $22.34/SF
− OpEx
−$17.9K −$5.59/SF
NOI
$53.6K $16.76/SF
Area
Chula Vista, CA
Vacancy
14.20%
Lease Rate
$26.04 /SF/Yr
Expense Ratio
25.00%
Simulate Cap Rate and NOI
Suggested Prices Based on Cap Rates
Cap rates vary significantly by property type, market, and asset quality.
Typical U.S. stable-market ranges:
Multifamily — 4.5% to 6.5% (Class A in primary markets often sub-5%; Class C in secondary markets 6%+)
Industrial / Logistics — 5.0% to 7.0% (compressed heavily in recent years due to e-commerce demand)
Office — 6.5% to 9%+ (wide spread post-2020; CBD Class A vs. suburban Class B varies dramatically)
Retail — 5.5% to 8.5% (grocery-anchored on the low end, unanchored strip centers higher)
Hospitality / Hotels — 7.5% to 10%+ (higher due to operational risk)
Self-Storage — 5.5% to 7.5%
Medical Office — 6.0% to 7.5%
Net Lease (single tenant, credit) — 5.0% to 7.0% depending on tenant credit and lease term
Rules of thumb:
Primary markets (NYC, SF, LA, Boston, DC) trade at lower cap rates than secondary/tertiary markets, often by 100–200 bps (bps, aka basis points; 1 bp = 0.01%).
Class A assets trade ~50–150 bps tighter than Class B, and Class B tighter than Class C.
Cap rates move inversely with price — a lower cap rate means a higher price for the same NOI.
Spread to the 10-year Treasury is a common benchmark; historically 200–400 bps over the 10-year.
Cap Rate 5%
$1,072,440
Cap Rate 7%
$766,029
Cap Rate 9%
$595,800
Alternative Uses
Best Use
Office B
$766.0K
$670.3K – $893.7K
NOI $53,622 @ 7.0% cap · market cap 3.35%
Second Best
—
—
no second resolved use
Theoretical Best
Office A
$1.02M
$893.0K – $1.19M
NOI $71,442 @ 7.0% cap · market cap 4.47%
Zoning and permitted uses should be independently verified with authorities.
Property Analytics
Unlock full access to Insights
Subscribe to Realmo Intelligence
Open Analytics
Current Use
Lease Details
Yes
Paved road access
Location Intelligence
Trade Area within ½ mile
542
Businesses Nearby
Explore this area
Business Placement
Demographics for 91913, CA
55,923
Population
17,880
Households
3.1
Avg Household Size
34
Median Age
40%
College-Educated
92%
High-School Grad
9.1 sq mi
ZIP Area
6,145
Density / Sq Mi
$129,412
Median Household Income
$56,058
Median Earnings
$2,863
Median Rent
$750,000
Median Home Value
Check the figures for this property
Cap Rate, Value Estimation, Potential NOI and more
View Realmo Analytics
Market
Vacancy Rate% for Office in West region
Questions? Ask Rey
Realmo’s AI knows this listing — price, zoning, demand, history. Ask anything.




Frequently Asked Questions
What type of property is this?
Office building - R-1-zoned property with on-site parking and access from Otay Lakes Road.
Where is this office building located?
The property is located at 845 Otay Lakes Rd Chula Vista, CA.
What is the asking price?
The asking price for this property is $1,600,000.
What are key features of this property?
This property features: 3,200‑square‑foot freestanding office building; R‑1 zoning with potential church, school, and nursing home uses identified; Approximately 42 on‑site parking spaces