Value-Add Duplex Investment
For Sale
$1,199,997
126 W 66th, Los Angeles, CA 90003
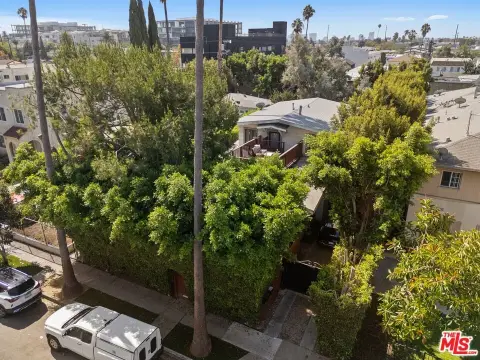
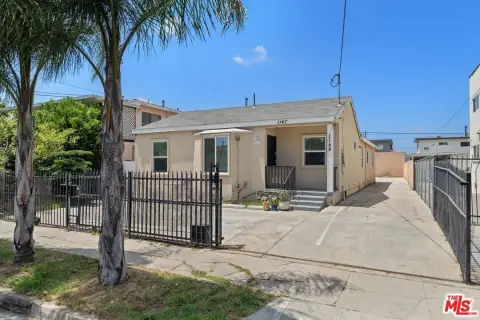
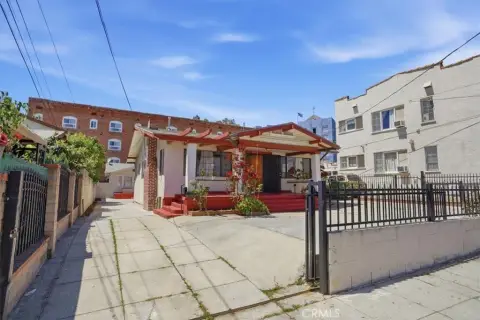
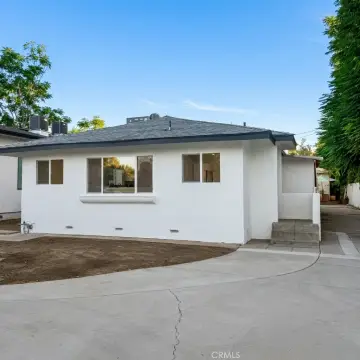
Single-story duplex with rental upside in Los Angeles.
Property Size2,790 SF
Days on Market193
Property Features for 126 W 66th
General Information
Standard status
Active
Size
2,790 SF
Property subtype
Duplex
Building Details
Building Size
2,790 SF
Year Built
2009
Listing Agency:
Will Wheaton Real Estate
Listed By:
Willie Wheaton · License #01857540
(213) 445-2277
Source:
Truthrealty
Added: Mar 23
Changed: Oct 1
Last Checked: Sep 30 at 6:09PM
Displayed information is deemed reliable but is not guaranteed and should be independently verified. All listing content including descriptions, pricing, images are the copyrighted material of Will Wheaton Real Estate
Investment Insights
Based on property information with market context.
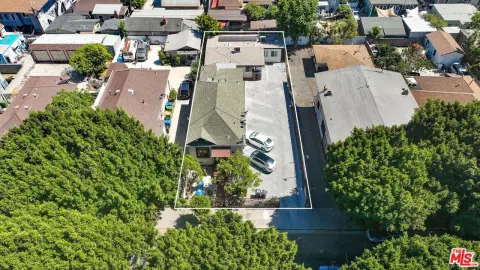
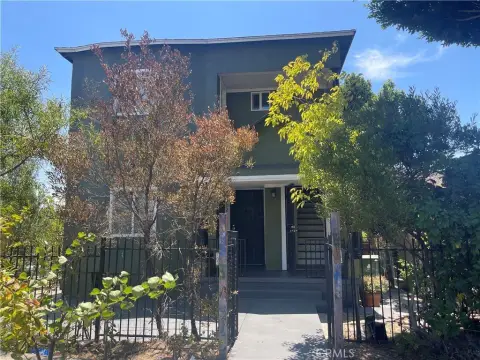
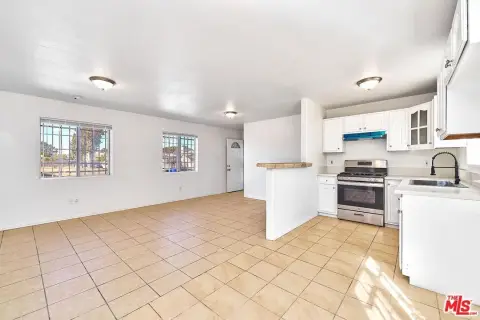
Located at 126 W 66th St in Los Angeles, this single-story duplex presents a value-add investment opportunity. Constructed in 2009, the well-maintained property features two spacious 4-bedroom, 2-bathroom units. The configuration is designed to attract strong tenant demand from larger households and shared living arrangements. Each unit offers functional layouts with ample living space, private garage parking, and practical amenities. The 2009 construction provides newer systems and improved building efficiency. Investors have the opportunity to increase income and improve overall returns as units turn over and rents are repositioned to market levels. Located in a dense rental corridor with convenient access to major transportation routes, employment centers, and neighborhood amenities, this property represents an opportunity for investors seeking a stable income-producing asset with long-term rent growth potential in the Los Angeles market.
Key Highlights
- Strong rental upside potential for increased income and returns.
- Newer construction (2009) reduces capital expenditures and maintenance costs.
- Two large 4‑bedroom, 2‑bathroom units attract high tenant demand.
Financial Insights
Estimated NOI and Cap Rate
NOI = area × lease_rate × (100 − vacancy) / 100 × (1 − expense_ratio). Net Operating Income — what the owner takes home each year before mortgage payments and income tax. Effective rent (asking rent minus vacancy losses) minus operating costs (taxes, insurance, maintenance, management).
NOI / Yr
$63,160
Cap rate = NOI / list price × 100. Capitalization rate — annual return on a fully cash purchase, before financing. NOI divided by price. Higher means more income per dollar invested, but usually also more risk or older condition. 5–8% is typical for stabilized commercial property; double digits often signal distressed deals.
Cap Rate
5.26%
Suggested Prices Based on Cap Rates
Cap rates vary significantly by property type, market, and asset quality.
Typical U.S. stable-market ranges:
Multifamily — 4.5% to 6.5% (Class A in primary markets often sub-5%; Class C in secondary markets 6%+)
Industrial / Logistics — 5.0% to 7.0% (compressed heavily in recent years due to e-commerce demand)
Office — 6.5% to 9%+ (wide spread post-2020; CBD Class A vs. suburban Class B varies dramatically)
Retail — 5.5% to 8.5% (grocery-anchored on the low end, unanchored strip centers higher)
Hospitality / Hotels — 7.5% to 10%+ (higher due to operational risk)
Self-Storage — 5.5% to 7.5%
Medical Office — 6.0% to 7.5%
Net Lease (single tenant, credit) — 5.0% to 7.0% depending on tenant credit and lease term
Rules of thumb:
Primary markets (NYC, SF, LA, Boston, DC) trade at lower cap rates than secondary/tertiary markets, often by 100–200 bps (bps, aka basis points; 1 bp = 0.01%).
Class A assets trade ~50–150 bps tighter than Class B, and Class B tighter than Class C.
Cap rates move inversely with price — a lower cap rate means a higher price for the same NOI.
Spread to the 10-year Treasury is a common benchmark; historically 200–400 bps over the 10-year.
Cap Rate 5%
$1,263,200
$1.3M
Cap Rate 7%
$902,286
$902.3K
Cap Rate 9%
$701,778
$701.8K
Market Conditions
NOI Build-Up for 2,790 SF
Vacancy — income lost from leasable area expected to sit empty during the year, subtracted from gross rent.
EGI (Effective Gross Income) — gross rent minus vacancy losses, the realistic income before paying operating costs.
OpEx (Operating Expenses) — recurring costs to operate the property (property tax, insurance, utilities, maintenance, management); excludes financing and capital improvements.
NOI (Net Operating Income) — income a property generates after operating costs but before financing and taxes.
Gross rent
$92.1K $33.00/SF
− Vacancy
−$1.8K −$0.66/SF
EGI
$90.2K $32.34/SF
− OpEx
−$27.1K −$9.70/SF
NOI
$63.2K $22.64/SF
Area
ZIP 90003
Vacancy
2.00%
Lease Rate
$33.00 /SF/Yr
Expense Ratio
30.00%
Simulate Cap Rate and NOI
Suggested Prices Based on Cap Rates
Cap rates vary significantly by property type, market, and asset quality.
Typical U.S. stable-market ranges:
Multifamily — 4.5% to 6.5% (Class A in primary markets often sub-5%; Class C in secondary markets 6%+)
Industrial / Logistics — 5.0% to 7.0% (compressed heavily in recent years due to e-commerce demand)
Office — 6.5% to 9%+ (wide spread post-2020; CBD Class A vs. suburban Class B varies dramatically)
Retail — 5.5% to 8.5% (grocery-anchored on the low end, unanchored strip centers higher)
Hospitality / Hotels — 7.5% to 10%+ (higher due to operational risk)
Self-Storage — 5.5% to 7.5%
Medical Office — 6.0% to 7.5%
Net Lease (single tenant, credit) — 5.0% to 7.0% depending on tenant credit and lease term
Rules of thumb:
Primary markets (NYC, SF, LA, Boston, DC) trade at lower cap rates than secondary/tertiary markets, often by 100–200 bps (bps, aka basis points; 1 bp = 0.01%).
Class A assets trade ~50–150 bps tighter than Class B, and Class B tighter than Class C.
Cap rates move inversely with price — a lower cap rate means a higher price for the same NOI.
Spread to the 10-year Treasury is a common benchmark; historically 200–400 bps over the 10-year.
Cap Rate 5%
$1,263,200
Cap Rate 7%
$902,286
Cap Rate 9%
$701,778
Alternative Uses
Best Use
Apartment 5plus
$49.33M
$43.16M – $57.55M
NOI $3,452,776 @ 7.0% cap · market cap 287.73%
Second Best
Multifamily LT 5
$902.3K
$789.5K – $1.05M
NOI $63,160 @ 7.0% cap · market cap 5.26%
Theoretical Best
—
—
same as Best Use
Zoning and permitted uses should be independently verified with authorities.
Property Analytics
Unlock full access to Insights
Subscribe to Realmo Intelligence
Open Analytics
Current Use
Location Intelligence
Trade Area within ½ mile
1,509
Businesses Nearby
Explore this area
Business Placement
Demographics for 90003, CA
72,764
Population
18,349
Households
4
Avg Household Size
30
Median Age
7%
College-Educated
53%
High-School Grad
3.6 sq mi
ZIP Area
20,212
Density / Sq Mi
$54,781
Median Household Income
$30,132
Median Earnings
$1,515
Median Rent
$547,600
Median Home Value
Check the figures for this property
Cap Rate, Value Estimation, Potential NOI and more
View Realmo Analytics
Market
Vacancy Rate% for Multifamily in West region
Questions? Ask Rey
Realmo’s AI knows this listing — price, zoning, demand, history. Ask anything.


Frequently Asked Questions
What type of property is this?
Duplex - Single-story duplex with rental upside in Los Angeles.
Where is this duplex located?
The property is located at 126 W 66th Los Angeles, CA.
What is the asking price?
The asking price for this property is $1,199,997.
What are key features of this property?
This property features: Strong rental upside potential for increased income and returns.; Newer construction (2009) reduces capital expenditures and maintenance costs.; Two large 4‑bedroom, 2‑bathroom units attract high tenant demand.